

Top Tech Companies in Delhi (1,981)
Mastercard powers economies and empowers people in 200+ countries and territories worldwide. Together with our customers, we’re building a resilient economy where everyone can prosper. We support a wide range of digital payments choices, making transactions secure, simple, smart and accessible. Our technology and innovation, partnerships and networks combine to deliver a unique set of products and services that help...

Mastercard's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue rose at double‑digit rates in 2025 and continued to increase at a similar pace in early 2026, supported by higher gross dollar volume, cross‑border activity, and switched transactions. The multi‑quarter trend indicates consistent top‑line momentum rather than a one‑off spike.
Profitability: Operating income outpaced revenue growth in 2025, expanding margins, while net income and EPS also advanced strongly. This points to operating leverage as volumes and higher‑yield cross‑border flows scale.
Diversified Revenue Streams: Value‑added services and solutions grew markedly faster than the core network, with security, digital authentication, analytics, and consulting cited as key contributors. This mix shift broadens growth beyond card payment fees and supports resilience.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising year over year in 2025 and accelerating to double‑digit growth in early 2026, with management raising its full‑year outlook. Bookings and room nights are also increasing, reinforcing the top‑line trend.
Profitability: Profitability expanded faster than revenue in 2025 and continued to improve in 2026, including margin expansion in the latest quarter. This indicates operating leverage and stronger earnings quality alongside growth.
Diversified Revenue Streams: B2B has been growing much faster than the consumer business, and advertising/media also expanded strongly in 2025. Multiple engines—B2B, lodging, and advertising—are contributing materially to overall expansion.
As the world’s largest asset manager, BlackRock partners with investors around the globe to help them (and those on whose behalf they invest) plan for life’s most important goals – like retirement, home ownership and their children’s education. Our clients range from governments, foundations and other large institutions to those investing on behalf of individuals, including firefighters, nurses, teachers and...

BlackRock's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in 2025 and accelerated further in early 2026, with adjusted operating income also rising. This points to broad-based top-line momentum beyond a single period.
Strong Market Position & Advantage: The company is characterized as the world’s largest asset manager with record-high assets under management and leading ETF scale. This scale advantage underpins continued client inflows and platform reach.
Diversified Revenue Streams: Growth is coming from multiple engines, including iShares ETFs, active strategies, private markets, and technology services such as Aladdin, alongside newer digital-asset offerings. This breadth reduces reliance on any single product line.
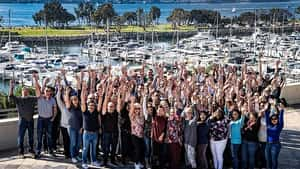
CSC is a global leader in providing business, legal, tax, and digital brand services to companies around the world. With more than 8,000 employees, CSC operates in more than 140 jurisdictions, delivering solutions that help businesses thrive. We pride ourselves on our client-focused approach, market-leading expertise, and unmatched global reach.
CSC's Top Stability & Growth Strengths
Strong Market Position & Advantage: Customer base is described as including a very large share of major global enterprises across Fortune-ranked companies, top brands, and leading private equity firms, indicating entrenched enterprise reach. This positioning underscores a strong competitive footing across multiple service lines.
Market Expansion: Operations have scaled to capabilities in more than 140 jurisdictions, aided by the approximately $3 billion Intertrust acquisition and its full integration in 2024. Continued investment and activity are highlighted across Europe, the Americas, Asia-Pacific, and the Middle East.
Product Line Growth: The company has expanded from incorporation services into corporate/legal compliance, fund administration, capital markets, tax, digital brand protection, domain services, and global subsidiary management. Corporate and Legal Solutions is described as the largest revenue-generating unit with a sizable workforce.
The power it has to uplift and bring people, Guided by our purpose - Celebrating real connections through delicious, planet-friendly food - we believe that working together with our teams, business and community partners will bring sustainable growth and positive change - today, tomorrow and for generations to come. As a privately owned family company with over 60 years of...

McCain Foods's Top Stability & Growth Strengths
Market Expansion: Multi-year capacity additions in Brazil, North America, and the UK, alongside acquisitions such as Penobscot McCrum and Forno de Minas, point to growing geographic reach and production footprint. The operating base spans dozens of facilities with sales in 160+ countries, underscoring continued expansion momentum.
Investor Backing & Capital Strength: Large-scale investments (e.g., R$1.8bn in Araxá and C$600m in Alberta) and ongoing M&A signal access to significant capital and an ability to fund growth. Credit commentary indicating sufficient cash flow to support expansion further reinforces financial capacity.
Strong Market Position & Advantage: The company is repeatedly characterized as the world’s largest manufacturer of frozen potato products, supported by a substantial global production and distribution network. This scale advantage supports resilience and the ability to capture demand across regions and channels.
.png)
Navan (Nasdaq: NAVN) is the leading all-in-one business travel, payments, and expense management platform that makes travel easy for frequent travelers. From finding flights and hotels to automating expense reconciliation, with 24/7 support along the way, Navan delivers an intuitive experience travelers love and finance teams rely on. See how Navan customers benefit and learn more at navan.com.

Navan's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is scaling at strong double-digit rates, reaching $702M in FY2026 and continuing to rise in subsequent quarters, with full‑year FY2027 guidance lifted into the low‑$900M range. Multiple updates indicate momentum in both reported results and outlook.
Healthy Cash Flow: Operating cash flow turned positive in FY2026 and free cash flow was also positive, alongside progress in non‑GAAP profitability in later quarters. These milestones suggest improving financial efficiency as scale increases.
Diversified Customer Base: The company reports 12,500+ active customers and continued wins with large enterprises across technology, manufacturing, and healthcare. This breadth points to demand resilience across multiple industries.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate FY2026 revenue rose 19% year over year to roughly $2.02B, with Q1 FY2027 revenue up 16% and ARR up 17%. This points to steady double‑digit expansion across both total and recurring revenue.
Customer Loyalty & Retention: Dollar-based net retention is reported around 110–111%, and ARR growth has tracked slightly ahead of revenue growth. These signals suggest existing customers are expanding usage alongside new logo additions.
Healthy Cash Flow: Company materials highlight strong free cash flow alongside growth, including substantial FY2026 free cash flow and robust margins in recent quarters. The business has also returned capital via notable share repurchases.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising from $1.62B in FY2023 to $2.17B in FY2024, $2.67B in FY2025, and about $3.35B in FY2026, with Q4 FY2026 up 25% year over year. This trajectory, alongside mid‑20% ARR growth, indicates continued expansion rather than a stall.
Healthy Cash Flow: Cash generation is growing, with free cash flow rising to about $779M in FY2026 and a free‑cash‑flow margin near 23%. Non‑GAAP operating metrics, including an ~80% gross margin, underscore operating leverage.
Strong Market Position & Advantage: Industry evaluations list the company as a Leader in the 2026 Gartner Magic Quadrants for both SSE and SASE, with five consecutive years of SSE leadership. Expanding large‑enterprise adoption and thousands of customers support a durable position in its core zero trust/SSE markets.
Dscout helps companies better understand the experiences people have with their products and brands in everyday life. Our SaaS video research platform helps our customers gather, manage, share and analyze millions of in-context moments submitted by people around the world.
Dscout's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Evidence indicates a $70M Series C in 2022 equipped the company to accelerate market expansion, product development, and hiring. Subsequent actions like the Panelfox acquisition reflect capacity to invest behind growth initiatives.
Product Line Growth: Product launches in 2026—such as AI Studio and Dscout MCP—extend the platform beyond traditional UX research into AI research/evaluation and broader organizational use. This broadening suggests an expanding addressable market and ongoing innovation momentum.
Strong Hiring & Retention: Workforce data shows headcount higher in 2026 than in 2023, alongside an uptick in active job postings. Increased posting cadence over recent years indicates continued investment in talent rather than a hiring pause.

Accuris gives engineers trusted answers, not just access. Our Engineering Intelligence platform combines verified data, actionable insights, and purpose-built workflows — so technical and business leaders can move faster, reduce risk, and make decisions they can defend.

Accuris's Top Stability & Growth Strengths
Strong Revenue Growth: Accuris reported it “substantially accelerated revenue growth” in 2024 and was on track to exceed its financial targets. It also described “exceptional momentum” in Q1 2025.
Product Line Growth: The company expanded its portfolio with Accuris Thread in 2025 and, in 2026, launched AI Assistant, BOM Intelligence, Change Impact Analysis, and a broader Engineering Intelligence platform. These moves indicate continued investment and expansion.
Market Expansion: Operational scale grew with a new Denver headquarters and offices in the UK, India, Malaysia, and Japan, alongside global headcount reaching 1,000+ across 20 countries. Accuris also reports 6,500+ organizations and 900,000 users, up from earlier disclosures.
TransUnion is a global information and insights company that makes trust possible by ensuring that each consumer is reliably and safely represented in the marketplace. We do this by having an accurate and comprehensive picture of each person. This picture is grounded in our legacy as a credit reporting agency which enables us to tap into both credit and public record...
TransUnion's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is consistently climbing across 2025 and into 2026, with management increasing full‑year guidance after stronger‑than‑expected quarters. Momentum is led by U.S. Financial Services and Emerging Verticals, with multiple quarters of high single‑ to double‑digit organic growth noted.
Profitability: Net income and adjusted earnings expanded alongside revenue, and adjusted EBITDA also increased. This points to improving operating leverage as growth scales across key segments.
Diversified Revenue Streams: Multiple business lines—including credit, fraud/identity, marketing, and international operations—are contributing to results. Expansion such as taking majority ownership in the Mexico bureau and broad-based U.S. segment strength reduce reliance on any single product or geography.
Flywire is a global payments enablement and software company. We combine our proprietary global payments network, next-gen payments platform and vertical-specific software to deliver the most important and complex payments for our clients and their customers.
Flywire's Top Stability & Growth Strengths
Strong Revenue Growth: Recent filings and earnings updates indicate sustained double-digit increases across annual and quarterly revenue, with momentum continuing into 2026. Guidance was raised during the year, reinforcing ongoing top-line expansion across core verticals.
Profitability: Results point to improving earnings quality, including a shift to positive net income on an annual basis and expanding adjusted EBITDA margins. Management also signaled further margin gains in 2026.
Customer Loyalty & Retention: Disclosures highlight a growing client base alongside net dollar-based retention that indicates expansion within existing customers. Wins across education, travel, healthcare, and B2B suggest durable relationships that support recurring growth.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Strong Revenue Growth: Optum’s consolidated revenue expanded from $253.0B in 2024 to $270.6B in 2025, indicating continued top-line growth. Multi‑year reporting also highlights ongoing increases at the consolidated level even as segment performance diverges.
Diversified Revenue Streams: Performance is spread across three businesses, with Optum Rx delivering substantial gains, Optum Insight growing modestly, and Optum Health contracting. This mix shows pharmacy and technology services helping sustain overall scale despite softness in care delivery.
Cost & Operational Efficiency: Operating performance improved in 2026 as Optum’s operating income rose year over year to about $4B in Q2 alongside reported gains in technology and clinical operations. UnitedHealth also raised its 2026 adjusted EPS outlook, signaling confidence in execution.
About Coursera: Coursera was launched in 2012 by Andrew Ng and Daphne Koller with a mission to provide universal access to world-class learning. Coursera partners with leading university and industry partners to offer a broad catalog of content and credentials, including courses, Specializations, Professional Certificates, and degrees. Coursera’s platform innovations — including AI-powered personalized guide and features, like Role Play and...
Coursera + Udemy 's Top Stability & Growth Strengths
Strong Market Position & Advantage: Scale of 290M+ learners and 12k–18k enterprise customers following the May 2026 combination signals a top-tier position in online learning. The combined platform also cites 95,000 creators and more than $1.5B of 2025 revenue, reinforcing competitive heft.
Strong Revenue Growth: Coursera delivered 9% revenue growth in 2025 and, after the Udemy combination, reported Q2 2026 revenue rose about 60% year over year. Management also raised full‑year 2026 reported revenue guidance to $1.220–$1.245 billion.
Diversified Revenue Streams: Multiple engines—consumer, enterprise, and subscriptions—are contributing, with Coursera’s consumer (+10%) and enterprise (+7%) segments growing in 2025. Udemy’s subscriptions (+8%) and Udemy Business revenue (+6%) expanded even as its consumer marketplace declined.
Citadel Securities is a technology-driven, next-generation global market maker. We provide institutional and retail investors with world-class liquidity, competitive pricing and seamless front-to-back execution in a broad array of financial products. Our teams of engineers, traders and researchers harness leading-edge quantitative research and the accelerating power of compute, machine learning and AI to power our analytics and tackle the market’s...
Citadel Securities's Top Stability & Growth Strengths
Strong Revenue Growth: Reported 2025 trading revenue rose to $12.2B from $9.7B in 2024, and 2026 featured record quarters such as a $7.3B Q2, indicating material topline expansion. EBITDA was also reported higher in 2025, reinforcing financial momentum.
Strong Market Position & Advantage: The company indicates it executes a substantial portion of daily U.S. equity and retail trading volumes and holds a top rank on Tradeweb for U.S. Treasury flows, underscoring entrenched scale. Leadership in listed options and as an NYSE Designated Market Maker further points to durable competitive advantage.
Market Expansion: New initiatives such as launching a High Touch Equities business in late 2025, opening an Amsterdam office in 2026, and operating across 50+ equity and fixed‑income markets signal active expansion. Ongoing hiring—1,800+ employees, dozens of open roles across regions, and the firm’s largest intern class—suggests continued investment in capacity.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.
ZS is a management consulting and technology firm that partners with companies to improve life and how we live it. We transform ideas into impact by bringing together data, science, technology and human ingenuity to deliver better outcomes for all. Founded in 1983, ZS has more than 15,000+ employees in over 40 offices worldwide.
ZS's Top Stability & Growth Strengths
Strong Hiring & Retention: Hiring and headcount are expanding, with disclosures of 15,000+ global employees, thousands of new hires, and third‑party estimates indicating continued workforce growth. Available evidence also points to active internal mobility and a recent increase in active job postings.
Market Expansion: Geographic and client footprints are broadening, with 40+ offices and 1,700+ customers across 170+ countries alongside concrete investments in new and expanded locations such as Hyderabad and Kingston. These moves indicate scaling delivery capacity in major capability centers and new regions.
Innovation-Driven Growth: The offering mix is shifting toward AI, data, technology, and platforms, including proprietary solutions and product capabilities. Strategic moves such as Salesforce-focused acquisitions and collaborations, plus a Tulip solution partnership, extend capabilities beyond traditional consulting.
We are a global investment research and financial data company with 40-plus offices across North America, Europe, Australia, and Asia. Our products and services are used daily by individual investors, financial advisors, asset managers, retirement plan providers, and institutional investors. We provide data, research, and analysis across managed investment products, publicly listed companies, private capital markets, debt securities, and real-time...
Morningstar's Top Stability & Growth Strengths
Strong Revenue Growth: Consolidated revenue has increased across recent years, with additional year-over-year gains extending into early 2026. This pattern indicates ongoing top-line expansion even as quarterly and annual growth rates vary.
Profitability: Operating income reached new highs in 2025 and continued to rise in subsequent quarters. This points to improving operating leverage alongside revenue growth.
Product Line Growth: Businesses such as Morningstar Credit, PitchBook, Retirement, and the Direct Platform are cited as key growth engines, with Credit standing out. This breadth of product contributions supports expansion beyond a single offering.
Tufin is a world leading network security policy management company, managing and automating security changes across next gen firewalls and network devices. We are a hybrid technology, supporting on/off prem and cloud services. The automation orchestration piece is what sets us apart in the market, as this allows us to help our customers to implement their security changes in hours...
Tufin's Top Stability & Growth Strengths
Strong Revenue Growth: Company updates describe double-digit revenue growth in 2024, back-to-back record years, and roughly 30% year-over-year new-business growth across 2024–2025. Momentum is further indicated by reported acceleration in cloud/SASE/microsegmentation activity.
Customer Loyalty & Retention: Customer net retention of 107% in 2025 suggests expansion within the existing base. This points to durable relationships with large enterprises across multiple industries.
Product Line Growth: The portfolio expanded via the 2024 acquisition of AKIPS and the addition of AI-driven capabilities, extending from policy management into broader network visibility and operations. Growth in cloud, SASE, and microsegmentation (reported at 2.5× in 2025) illustrates traction for newer offerings.
SentiLink is the leading fraud intelligence company, providing financial institutions and fintechs with purpose-built solutions for identity verification and fraud prevention. Our products detect synthetic fraud, identity theft, and hard-to-detect first-party fraud in real time — helping partners stop losses before they happen while approving more legitimate customers. Founded in 2017 by Naftali Harris and Max Blumenfeld, creators of the risk...

SentiLink's Top Stability & Growth Strengths
Market Expansion: Public materials indicate expansion from serving 100+ organizations in 2022 to 400+ institutions by 2025, including moves into telecom and government with FedRAMP Ready status enabling federal opportunities. Evidence also points to deeper enterprise reach, including 11 of the 15 largest U.S. banks and 6 of the top 10 credit unions.
Product Line Growth: The offering has broadened from synthetic identity fraud into identity theft, first‑party fraud, and a CIP/KYC suite (e.g., CIP Match & Watchlists), later adding analyst tooling like Intercept. These additions expand addressable use cases across financial services and adjacent verticals.
Strategic Partnerships: Ecosystem ties include a FICO Industry Vanguard Decision Award with direct integration of SentiLink’s Identity Theft Score into the FICO Marketplace, alongside collaborations such as Yardi, Taktile, and a state‑level selection by Florida’s AHCA. These channels and validations open distribution and reinforce product relevance with large enterprises.



