

Top Tech Companies in Delhi (2,008)

In 1939, Bill Hewlett and Dave Packard, college friends turned business partners, started the original Silicon Valley startup in the space of a rented Palo Alto garage. Starting with audio oscillators, the friends built the foundation for a company that would grow to become a global leader in enterprise technology. More than 75 years later, our success is exemplified through...
Hewlett Packard Enterprise's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate sales are rising sharply, with fiscal Q3 2026 revenue increasing significantly year over year and management lifting its revenue outlook for both FY2026 and FY2027. Growth is broad-based across servers, networking, and the Cloud & AI segment, underscoring strong top-line momentum.
Profitability: Operating performance has strengthened materially, with operating profit up sharply and margins expanding in the latest quarter. Guidance points to continued non-GAAP earnings growth into FY2027, suggesting improved earnings durability.
Healthy Cash Flow: Cash generation is strengthening, with free cash flow rising to about $1.0B in the latest quarter. The outlook targets at least $5B of free cash flow in FY2027, signaling robust internal funding capacity.
Vantor is forging the new frontier of spatial intelligence to unlock a more autonomous, interoperable world. We empower decision makers and operators with the clarity they need to navigate what’s happening now and shape what’s coming next. Our AI-powered spatial intelligence platform fuses data from the world’s highest-resolution satellites with real-time sensor feeds from space, air, and ground to create...
Vantor's Top Stability & Growth Strengths
Market Expansion: International business is described as growing at a double-digit rate in 2025, with more than 60 government partners and over a dozen new European customers broadening geographic reach. Partnerships and a planned joint venture in Germany further extend presence across Europe.
Customer Loyalty & Retention: Follow-on and option-year awards—such as the $70 million NGA G-EGD option and the U.S. Army’s up-to-$217 million One World Terrain production award—indicate repeat demand and sustained relationships. These multiyear arrangements suggest durable engagement even when full contract ceilings are not immediately realized.
Product Line Growth: The launch of Tensorglobe and AI-enabled products (Raptor, Sentry) alongside planned Vantage and Pulse constellations expands offerings beyond imagery into software, analytics, and higher-revisit capacity. This broadening portfolio creates additional avenues for growth even though near-term revenue contribution is not quantified.
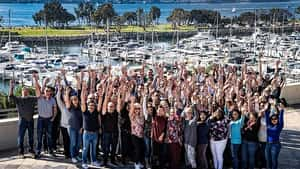
CSC is a global leader in providing business, legal, tax, and digital brand services to companies around the world. With more than 8,000 employees, CSC operates in more than 140 jurisdictions, delivering solutions that help businesses thrive. We pride ourselves on our client-focused approach, market-leading expertise, and unmatched global reach.
CSC's Top Stability & Growth Strengths
Market Expansion: Capabilities in more than 140 jurisdictions, the completed Intertrust integration, and investment in a larger Luxembourg office indicate sustained geographic scale-up. Acquisitions such as Intertrust and Eddystone broadened presence across Europe and Asia-Pacific while deepening local delivery.
Strong Market Position & Advantage: Adoption by a large majority of major enterprises and top global brands, plus category strength in registered agent and enterprise domain management, point to entrenched competitive standing. Independent industry recognition in capital-markets operations further underscores visibility in core niches.
Investor Backing & Capital Strength: Independent credit analyses reference mid‑single‑digit organic growth expectations, high profitability, and a large recurring-revenue base, supporting stable financing capacity. Deleveraging and an upgrade from a major ratings agency suggest solid access to capital and prudent balance‑sheet management.
As the world’s largest asset manager, BlackRock partners with investors around the globe to help them (and those on whose behalf they invest) plan for life’s most important goals – like retirement, home ownership and their children’s education. Our clients range from governments, foundations and other large institutions to those investing on behalf of individuals, including firefighters, nurses, teachers and...

BlackRock's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a double‑digit pace, including approximately 19% year‑over‑year growth in both Q3 2026 and full‑year 2025. Momentum is supported by organic fee growth, performance fees, and growing technology revenue.
Strong Market Position & Advantage: Scale is expanding with AUM around $15.5 trillion and about $869 billion of net inflows over the 12 months through Q3 2026, indicating robust client demand. Being the world’s largest asset manager reinforces distribution reach and product adoption.
Diversified Revenue Streams: Growth spans ETFs, private markets (infrastructure and private credit), active fixed income, systematic strategies, and technology subscriptions such as Aladdin. Technology and data services are contributing meaningfully, with tech revenue up about 14% year over year.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased 8% in 2025 and accelerated to 14% year over year in Q2 2026, with management raising full‑year revenue guidance to $16.05–$16.22 billion. Gross bookings also rose 8% in 2025 and 12% in Q2 2026, indicating expanding underlying travel activity.
Profitability: Operating income grew 42% in 2025 and surged 65% in Q2 2026, while GAAP net income jumped 166% in that quarter. Adjusted EBITDA rose 19% in 2025 and 23% in Q2 2026, suggesting improved operating leverage alongside growth.
Diversified Revenue Streams: Both distribution channels are contributing, with Q2 2026 B2B gross bookings up 21% (B2B revenue up 23%) and B2C gross bookings up 8%. Lodging remained a key driver as lodging gross bookings rose 11% and booked room nights increased 6% in Q2 2026.
.png)
Navan (Nasdaq: NAVN) is the leading all-in-one business travel, payments, and expense management platform that makes travel easy for frequent travelers. From finding flights and hotels to automating expense reconciliation, with 24/7 support along the way, Navan delivers an intuitive experience travelers love and finance teams rely on. See how Navan customers benefit and learn more at navan.com.

Navan's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding strongly over multiple years, with recent quarters delivering double-digit increases and an upgraded full‑year outlook. Underlying demand also appears robust as gross booking volume and new signed enterprise bookings have risen sharply.
Market Expansion: The customer base has grown to more than 12,500 with record new signed enterprise bookings and expansion into regions such as Europe and India. Added offerings like meetings and events further broaden the company’s reach across segments and geographies.
Healthy Cash Flow: Operating cash flow and free cash flow turned positive for the latest full fiscal year, and the company reported positive cash generation in a recent quarter. This suggests improving operating leverage even as the business scales.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Historical 2022 results showed robust year-over-year expansion, and leadership later indicated the business was heading toward about $2 billion in revenue. These signals indicate meaningful scale and ongoing momentum.
Innovation-Driven Growth: AI product adoption and platform usage have surged since 2023, with a sizable share of customers upgrading to new AI capabilities. Company disclosures describe sharp increases in monthly active AI users and total interactions analyzed on the platform.
Market Expansion: Completion of the $6.75B Press Ganey Forsta acquisition broadens reach into healthcare experience data, relationships, and analytics. This materially expands the company’s footprint and opportunities for cross-sell.
HERE Technologies is a location data and technology company that created the first digital map over 35 years ago. Today we are the world's leading location platform company with a global footprint across 52 countries. Although our strongest presence is in the automotive industry, we also work with leading companies across a wide range of industries, including transport and logistics,...
HERE Technologies's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent industry rankings place the company at the top of location-platform evaluations for nine consecutive years, reinforcing sustained competitive strength. Scale indicators note its platform in 238 million vehicles by 2026 and leadership recognition across most evaluation categories.
Market Expansion: Automotive reach broadened to 238 million vehicles worldwide by 2026, with more than 63 million using its data for ADAS and automated driving. Customer penetration includes all 10 of China’s top vehicle exporters in 2025, indicating deeper access to a key growth market.
Strategic Partnerships: A 10-year, $1 billion cloud agreement with AWS, an expanded Hyundai AutoEver online-navigation program covering 1+ million vehicles, and collaborations with Samsara and Esri highlight expanding distribution and co-innovation. These alliances support scale in automotive, logistics, and AI-enabled location services.
ZS is a management consulting and technology firm that partners with companies to improve life and how we live it. We transform ideas into impact by bringing together data, science, technology and human ingenuity to deliver better outcomes for all. Founded in 1983, ZS has more than 15,000+ employees in over 40 offices worldwide.
ZS's Top Stability & Growth Strengths
Strong Hiring & Retention: Headcount and hiring momentum are evident, with third-party estimates showing growth from roughly the mid‑teens of thousands in 2024 to 20,000+ by 2025–2026 and plans to hire thousands, alongside new capacity such as the Hyderabad operations center. This suggests the company is scaling delivery and talent depth across geographies.
Innovation-Driven Growth: The firm has expanded into AI and digital offerings, including its ZAIDYN platform, acquisitions like Digital Additive and Torrent Consulting, and launches such as Myelo developed with the International Myeloma Foundation. These moves indicate investment beyond traditional consulting into scalable, tech‑enabled services.
Market Expansion: A dedicated mid‑cap pharmaceutical vertical and the opening of an operations center in Hyderabad point to deliberate expansion in target segments and delivery footprint. These steps signal efforts to broaden served markets and strengthen execution capacity.

Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Profitability: Operating earnings and margins improved notably in 2026, with Q3 operating earnings up sharply year over year and the operating margin rising to 5.6%. Feedback suggests earnings resilience is being supported by operational changes and a shifting business mix.
Strong Revenue Growth: Reported annual revenue expanded from $226.6B in 2023 to $270.6B in 2025, including roughly 12% growth in 2024 and 7% in 2025. This establishes a robust multi‑year revenue trajectory even as recent growth rates have moderated.
Cost & Operational Efficiency: Cost controls and operational improvements are described as lifting earnings despite lower revenue in 2026. Optum Health’s operating earnings rose from $41M to $735M year over year while serving fewer value‑based patients, indicating stronger execution.
TransUnion is a global information and insights company that makes trust possible by ensuring that each consumer is reliably and safely represented in the marketplace. We do this by having an accurate and comprehensive picture of each person. This picture is grounded in our legacy as a credit reporting agency which enables us to tap into both credit and public record...
TransUnion's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has risen consistently, with annual growth in the high single digits and the latest quarter showing double-digit year-over-year increases, and management raising full-year growth guidance. Organic constant-currency expansion in the latest quarter indicates underlying momentum beyond acquisitions and FX.
Profitability: Profitability is improving alongside sales, as net income and adjusted diluted EPS increased year over year in the latest quarter. Full-year results also showed higher net income and adjusted EBITDA.
Market Expansion: Growth appears across U.S. Markets and internationally, with U.S. Financial Services leading and international results positive on an organic constant-currency basis. The company is extending its reach through moves such as acquiring a majority stake in Trans Union de México.

Tune into the innovation, collaboration and culture that our team members bring to the office every day. We want you to be a part of our journey to build the next generation of technology that transforms the way the world communicates. Our team members are the key to our history of groundbreaking innovation and our continued progress. If you bring...

EchoStar's Top Stability & Growth Strengths
Cost & Operational Efficiency: Operating performance indicators such as adjusted OIBDA improved materially despite lower revenue, including a shift in wireless from negative to positive OIBDA. This points to tighter cost control and progress in operational execution.
Strategic Partnerships: Major arrangements with AT&T and SpaceX establish a hybrid wireless model and prospective satellite-to-device capabilities for Boost Mobile. These relationships expand network reach and optionality without the full cost of standalone nationwide buildouts.
Investor Backing & Capital Strength: A completed spectrum sale to AT&T delivering multibillion-dollar cash proceeds provides liquidity to address obligations and reinvest. This asset monetization strengthens near-term financial flexibility even as the business mix evolves.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue and annual recurring revenue each rose 25% in fiscal 2026, with fourth-quarter revenue also up 25% year over year. Management still expects continued double-digit growth in fiscal 2027, albeit at a slower pace.
Healthy Cash Flow: Operating cash flow reached about $1.13 billion and free cash flow was roughly $779.1 million in fiscal 2026. This points to robust cash generation alongside expansion.
Product Line Growth: The platform is expanding into AI security, data security, SASE, and agentic security operations. Security-for-AI bookings were reported to increase more than 50% sequentially in the fourth quarter, indicating early traction.
A global leader in applied safety science, UL Solutions transforms safety, security and sustainability challenges into opportunities for customers in more than 100 countries. UL Solutions delivers testing, inspection and certification services, together with software products and advisory offerings, that support our customers’ product innovation and business growth. The UL Certification Marks serve as a recognized symbol of trust in...

UL Solutions's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased from $2.678B in 2023 to $3.053B in 2025 and continued to rise 5.2% year over year in Q2 2026, with organic growth of 6.6%.
Profitability: Adjusted EBITDA rose 20.7% in 2025 to $792M and grew 11.2% in Q2 2026, with margin expansion to about 26.8% alongside higher adjusted net income.
Market Expansion: The company is expanding its footprint through acquisitions and capacity investments, including completing the Eurofins Electrical & Electronics business in October 2026 and enlarging testing facilities.

CrowdStrike has redefined security with the world’s most advanced cloud-native platform that protects and enables the people, processes and technologies that drive modern enterprise. Tested and proven, the world's largest organizations trust CrowdStrike to stop breaches with unparalleled protection against the most sophisticated cyberattacks. The CrowdStrike culture has been built upon our Core Values since the day we began. We...
CrowdStrike's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 26% year over year to about $1.47B in Q2 FY2027, while ARR increased roughly 25% to $5.84B and the full‑year outlook was raised. These indicators point to durable top‑line momentum across recent quarters and fiscal years.
Healthy Cash Flow: Quarterly free cash flow increased to about $377M (from ~$284M a year earlier) and operating cash flow reached roughly $530M. Rising cash generation alongside growth supports operating flexibility and investment capacity.
Product Line Growth: Adoption across the Falcon platform is deepening, with record net new ARR of about $333M (+51% YoY) and rapid expansion in offerings such as Falcon Flex ARR (exceeding ~$2.29B, up ~101% YoY). Cloud and identity security ARR also expanded meaningfully, indicating broader portfolio traction.

About Coursera: Coursera was launched in 2012 by Andrew Ng and Daphne Koller with a mission to provide universal access to world-class learning. Coursera partners with leading university and industry partners to offer a broad catalog of content and credentials, including courses, Specializations, Professional Certificates, and degrees. Coursera’s platform innovations — including AI-powered personalized guide and features, like Role Play and...
Coursera + Udemy 's Top Stability & Growth Strengths
Strong Market Position & Advantage: Strong Market Position & Advantage: Scale is described as more than 290–300 million learners and roughly 18,000 enterprise customers after the May 2026 combination, indicating extensive reach across consumer and enterprise learning. The combined catalog spans university-backed credentials and a large instructor marketplace, supporting broad coverage of professional skills and AI-focused training.
Cost & Operational Efficiency: Cost & Operational Efficiency: Guidance points to approximately $115 million in annual cost synergies within 24 months of closing and an adjusted EBITDA margin target of about 14% for 2026. Udemy’s return to positive GAAP net income in 2025 further indicates an improving profitability trajectory for the combined business.
Innovation-Driven Growth: Innovation-Driven Growth: AI-related learning is expanding rapidly, with Udemy reporting 120% growth in AI course enrollments and Coursera citing a 33% increase in micro-credential enrollments. Subscription-led offerings and professional certificates are highlighted as key drivers of engagement and recurring revenue.

Bounteous is a global AI Services firm where agentic engineering and human experience converge to deliver transformative business outcomes for the enterprise. We help organizations design, build, and scale AI-driven products, platforms, and processes. With more than 5,000 team members worldwide, Bounteous delivers AI that sticks, powering adoption and outcomes that move organizations from experimentation to true transformation.

Bounteous's Top Stability & Growth Strengths
Market Expansion: Mergers and acquisitions have broadened global reach and scale, highlighted by the Accolite combination and the Cartesian acquisition adding specialists across North America and Europe. Active recruitment and an international footprint across the Americas, EMEA, and APAC reinforce an expanding operational presence.
Innovation-Driven Growth: A clear pivot toward enterprise AI, data analytics, and agentic engineering is emphasized through new capabilities and practices. Joining Anthropic’s Claude Partner Network underscores investment in AI-led services even if specific revenue impact is not disclosed.
Strategic Partnerships: High-profile ecosystem ties, including a launch Preferred Services Partner role with Anthropic and additional tech alliances such as Pendo, are positioned to enable enterprise-scale programs. These partnerships are presented as deepening credibility and opening growth pathways without quantifying near-term contribution.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investment capital is reported at approximately $77 billion as of October 1, 2026, and assets rose from $26 billion in 2015 to $67 billion by 2025. These figures point to substantial scale and a sustained ability to attract and retain capital.
Strong Hiring & Retention: Employee headcount at Citadel Advisors increased from 3,153 in 2024 to 3,284 in 2025. This pattern indicates active workforce expansion to support growing operations.
Market Expansion: The firm is exploring new opportunities, including discussions to acquire U.S. oil‑production assets, and plans to add Dubai as a new location. These moves signal continued broadening of its geographic and business footprint.
Our Mission: Create a world where everyone has an authentic digital identity. Identity Digital is an internet infrastructure company that makes sure web addresses work seamlessly. If we do our job right, we are invisible to the user. We have the world’s largest portfolio of nearly 300 TLDs like .info, .pro, .world, which lets people and businesses build, market, and own...
Identity Digital's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as having grown in 2025, with a substantial portion of incremental revenue flowing to the bottom line, indicating operating leverage. The exact rate is not disclosed, making this a directional rather than quantified indicator.
Market Expansion: Applications for 216 new TLDs and the award to operate .us (with about two million domains transitioning) point to active expansion of addressable markets and services. These actions signal investment and commercial wins even though applications are not guaranteed launches.
Investor Backing & Capital Strength: A December 2025 continuation-vehicle transaction by Ethos Capital brought in multiple institutional investors to support the company’s next phase. This suggests capacity to fund growth initiatives such as new TLD applications and major registry migrations.
Tufin is a world leading network security policy management company, managing and automating security changes across next gen firewalls and network devices. We are a hybrid technology, supporting on/off prem and cloud services. The automation orchestration piece is what sets us apart in the market, as this allows us to help our customers to implement their security changes in hours...
Tufin's Top Stability & Growth Strengths
Strong Revenue Growth: Company disclosures indicate double-digit revenue growth in 2024 and continued momentum via 30% year-over-year new-business growth in 2025. Reported 107% net retention further supports expansion of recurring revenue within the existing base.
Market Expansion: Reported 2.5× growth in cloud, SASE, and microsegmentation in 2025 points to traction beyond traditional network-policy management. Ongoing AI-driven launches and partnerships in 2025–2026 reinforce expansion into adjacent markets.
Customer Loyalty & Retention: A 2025 customer net retention rate of 107% suggests existing accounts expanded their spend after churn and contractions were accounted for. An NPS of 71, up sharply year over year, indicates rising advocacy alongside retention.



